If you're investing in rental properties, you may be considering purchasing your next property through a limited liability company (LLC). An LLC can help you organize your real estate investments, separate business activities, and manage multiple properties. But can you get a mortgage under an LLC? Yes. Many DSCR lenders allow eligible investment properties to be purchased or refinanced in the name of an LLC. This makes DSCR financing an attractive option for real estate investors who prefer to hold their rental properties through a business entity. However, lender requirements vary, and there are several things to understand before applying.
Published on 10/26/2026
Explore 2026 home design trends, from curved architectural details and natural materials to wellness spaces and energy efficient features.
Published on 10/26/2026
If you're planning to purchase or refinance a rental property, one of the most important factors in qualifying for a DSCR loan is your Debt Service Coverage Ratio (DSCR). Unlike traditional investment property mortgages that typically evaluate personal income and debt-to-income ratios, DSCR loans focus primarily on whether the property's rental income can support its mortgage payment. But what DSCR ratio do you actually need to qualify? The answer depends on the lender and loan program. Some programs may allow a DSCR below 1.00, while others offer their best terms to borrowers with stronger rental cash flow. Understanding how the ratio works can help you evaluate a potential investment property before applying for financing.
Published on 10/19/2026
Unlock your home's equity today and capture lower interest rates tomorrow through smart refinancing.
Published on 10/19/2026
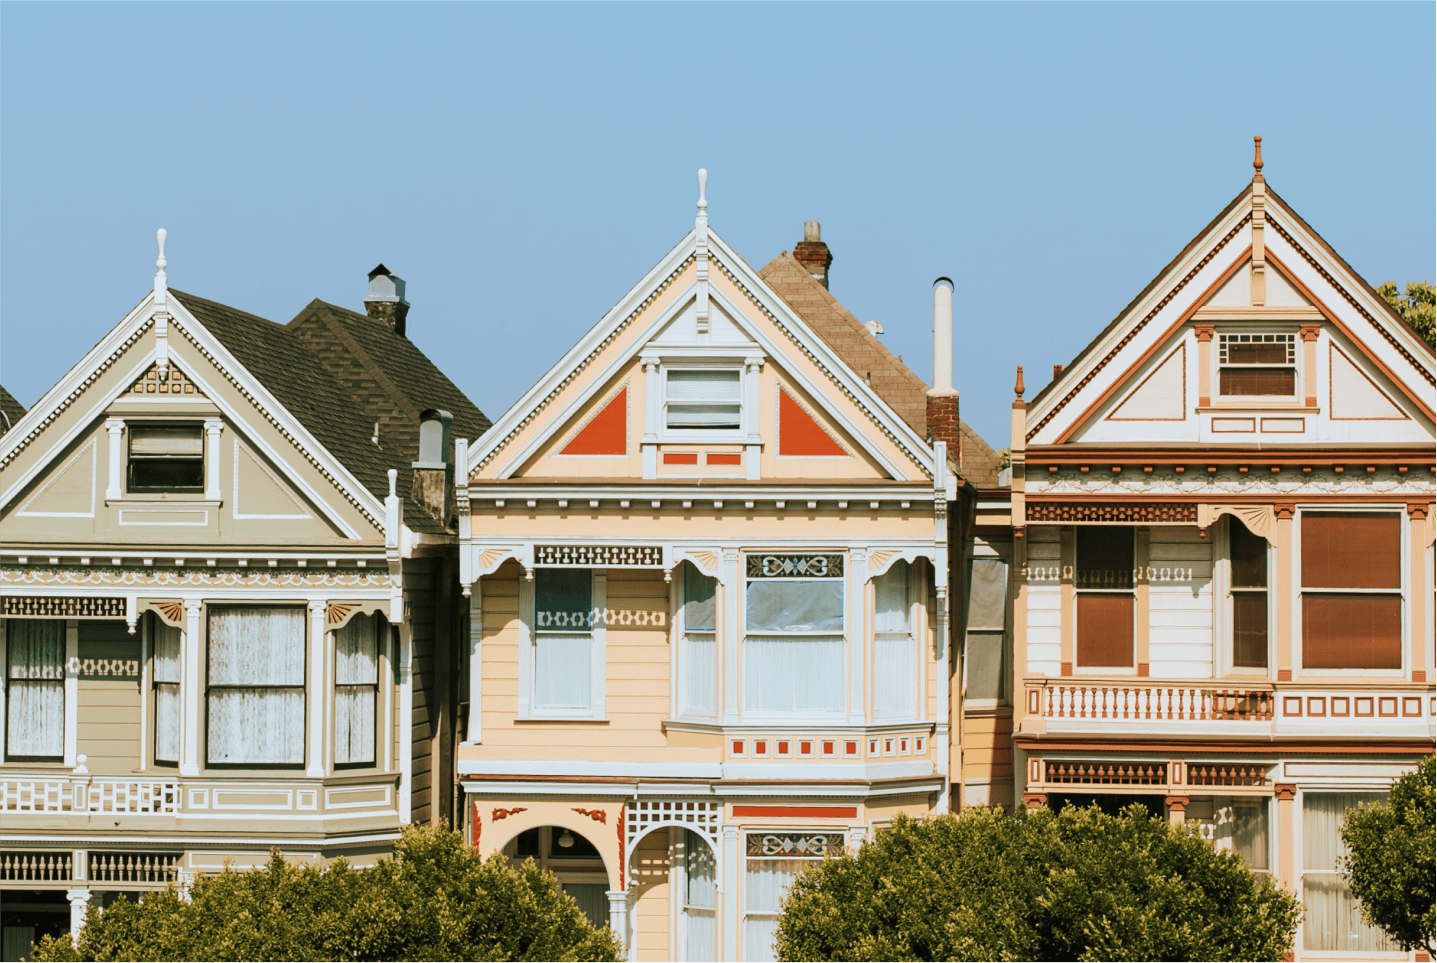
If you're looking to purchase or refinance a three-family investment property in New Jersey, a DSCR loan may be a financing option worth exploring.
Published on 10/12/2026
Skip the hype and AI fluff. Discover 2026-savvy, non-obvious ways to choose a Realtor who actually delivers results.
Published on 10/11/2026
Yes. You can absolutely buy a home in New Jersey with 5% down, and for many buyers, putting 5% down can be a smart alternative to waiting years to save 20%. The right down payment depends on your loan program, credit profile, income, purchase price, and overall financial situation. The key is understanding the trade-offs before deciding how much money to put into the house.
Published on 10/05/2026
Smart 2026 credit moves to help homebuyers protect their credit profile while moving and preparing for a mortgage.
Published on 10/05/2026
Unlocking your home’s equity can be a game-changer. If financial challenges are holding you back, this strategy may help ease your burdens and pave your path forward.
Published on 09/28/2026
